Cursor Valued at $29B: Doesn't Build AI, Yet Becomes AI's Biggest Winner
Cursor doesn't train models—it rents AI capabilities to build a coding tool, with a 12x valuation surge and over $1B in revenue in a year.
Cursor's valuation rose from $2.5B to nearly $29B in under a year—about 12x—with annual revenue exceeding $1B. It doesn't train AI models itself but rents models from Anthropic, OpenAI, and Google, packaging model capabilities into a handy coding tool through engineering work like codebase indexing, context management, and multi-model orchestration. The article argues this case shows that as foundation models become commoditized, the richest valuations flow to the application layer closest to users, not to model trainers. For entrepreneurs, you don't need to build your own models to create a high-value product—the prerequisite is making that "window" good enough.
An observation from a YouTube short sparked considerable discussion among developers: the code editor Cursor's valuation has climbed from $2.5 billion last December to nearly $29 billion—roughly a 12x increase in under a year. What's more intriguing is how it makes money—Cursor doesn't train AI models itself. It's more like a window through which users type code, and the intelligence behind that window comes from Anthropic, OpenAI, and Google.
A 12x Valuation Surge: The Victory of the Application Layer
According to the video, Cursor's valuation climbed from $2.5 billion to nearly $29 billion in under a year—roughly a 12x increase. That figure stands out across the entire AI industry. The video's explanation is straightforward: the richest valuations go to the topmost application layer, not to the party actually training the AI.
This actually points to an easily overlooked industry structure issue. Over the past two years, the spotlight has mostly been on foundation model companies—whose model has more parameters, higher benchmark scores, longer context. But Cursor's case shows that as model capabilities converge, what users are truly willing to pay for is the interface that packages those capabilities into a handy tool. Developers don't care which company's model is being called behind the scenes; they care whether autocomplete is accurate, responses are fast, and the codebase understanding is thorough.
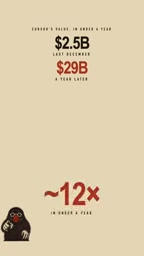
Intelligence Is Rented: Cursor's True Role
One line in the video captures it precisely: Cursor is "the window you type into." It rents those models and pays for them. In other words, Cursor's core asset isn't model weights—it's product experience, engineering integration, and user habits.
This model is often compared to being a "wrapper," but there's a clear difference. A simple wrapper just takes an API and resells it, lacking any moat; Cursor, by contrast, has done extensive engineering work at the editor level—codebase indexing, context management, multi-model orchestration, interaction design—and these are what keep users around. The models are rented, but the effort to organize them into a usable programming environment is built in-house.
From a business perspective, this "renting intelligence" model has a clear but fragile cost structure: model invocation fees are real expenses, and if upstream providers raise prices or change licensing terms, profit margins get squeezed. The video doesn't elaborate on this, but it's an unavoidable question when assessing Cursor's long-term value.
The term "wrapper" carries a negative connotation in AI application circles, usually referring to products that merely forward API calls without adding substantive value. The key to judging whether an application is just a wrapper is whether it has built engineering barriers independent of the underlying model. Cursor's codebase indexing requires building a vectorized semantic retrieval layer for each project; context management must select the most relevant file fragments within a limited token budget; multi-model orchestration must choose the most cost-effective model for different tasks like autocomplete, chat, and refactoring. These capabilities can't be obtained through a single API call—they require sustained engineering investment and user feedback iteration, and it's precisely this work that separates a "window" from a "wrapper."
Revenue Is Real: Annual Revenue Exceeds $1 Billion
For a valuation story to hold up, it needs revenue support. The video explicitly states that Cursor's annual revenue has exceeded $1 billion, emphasizing that "the revenue is real." This is crucial—it distinguishes Cursor from AI products that have only user growth without a monetization path.
Developers paying for programming tools has historical precedent—from IDE licenses to various plugin subscriptions, this market has always existed. AI coding assistants simply amplify this willingness to pay: when a tool genuinely saves time, the subscription fee feels worthwhile. Cursor is tapping into exactly this mental accounting.
Subscription-based SaaS valuations are typically measured as multiples of ARR (Annual Recurring Revenue). The reason Cursor's annual revenue exceeding $1 billion is repeatedly emphasized is that it corresponds to predictable cash flow, not a one-time financing or user-count story. Against the backdrop of widespread skepticism about "high growth, low retention" in AI applications, coding tools have relatively stronger payment stickiness: once developers embed an editor into their daily workflow, switching costs include reconfiguration, re-adapting to keyboard shortcuts, and rebuilding codebase indexes—making subscription renewal rates often higher than those of general-purpose AI products.
What This Means for AI Entrepreneurs
Cursor's path raises a question worth pondering: as foundation models become increasingly commoditized, where will value settle? The video's answer leans toward the application layer—whoever is closest to users, whoever controls the interface and habits, is more likely to command high valuations.
But this doesn't mean model companies lose out. Anthropic, OpenAI, and Google gain real invocation revenue through downstream applications like Cursor, essentially outsourcing distribution to teams that understand developers better. This is a division of labor, not a zero-sum game.
For entrepreneurs, Cursor's case shows: you don't have to train your own models to build a high-value product. Organizing existing capabilities into tools that solve specific pain points can also support substantial commercial scale. The prerequisite is that the "window" must be good enough that users don't want to switch.
Foundation model "commoditization" refers to the trend of different vendors' models gradually converging in capability, intensifying price competition, and lowering switching costs. When models themselves struggle to differentiate, value in the industry chain shifts to both ends: one end is the model trainers who control compute and data, the other is the application layer that controls user interfaces and workflows. Cursor sits in the latter. This pattern has precedent in the cloud computing era—companies like Snowflake and Datadog grew on top of AWS with high market caps; they likewise don't own the underlying infrastructure, yet achieved valuation multiples far exceeding infrastructure providers through product design closely tied to specific scenarios.
One-line Summary
Cursor doesn't train models—it rents AI capabilities to build a coding tool, with a 12x valuation surge and over $1 billion in revenue in a year.
Paragraph Summary
Cursor's valuation rose from $2.5 billion to nearly $29 billion in under a year, roughly a 12x increase, with annual revenue exceeding $1 billion. It doesn't train AI models itself but rents models from Anthropic, OpenAI, and Google, packaging model capabilities into a handy coding tool through engineering work like codebase indexing, context management, and multi-model orchestration. The article argues this case shows that as foundation models become commoditized, the richest valuations flow to the application layer closest to users, not to model trainers. For entrepreneurs, you don't need to build your own models to create a high-value product—the prerequisite is making that "window" good enough.
Related articles

Microsoft WebIQ: Verifiable Real-Time Web Grounding for AI Agents
Microsoft WebIQ gives AI Agents real-time, citable web grounding across web, news, images, videos, and Places—164ms P95 latency, 50% fewer tokens, Scopes source control, and MCP integration.

Augmentable Gaussian Splatting: Building Photorealistic Simulation Environments for Robot Training
Team combines Gaussian Splatting with meshes to build photorealistic robot simulation environments, integrating MuJoCo Warp physics and Franka Panda for augmentable, relightable real-site simulation.

Gemini 4 Carbon Released: The Leap from Gemini 3 to Gemini 4 in Under a Year
Google releases Gemini 4 Carbon, less than a year after Gemini 3. In the official demo, Carbon reverse-engineered the Theme Park binary, added a new DeepMind-themed ride, and ported it to the web in one shot.