The $90 Billion Compute Bill Behind Anthropic's $85 Billion IPO
Anthropic plans to net about $85 billion via IPO and private placement to fund $9 trillion in compute commitments.
Anthropic's IPO prospectus shows rapid growth alongside massive commitments: 825 million shares at $70–$78 plus $10 billion each from Google and Nvidia yield about $85 billion net. Revenue hit roughly $33.2 billion in the first nine months of 2026, up about 13x, with four-fifths usage-based. Operating cash flow swung to $6.6 billion inflow while an operating loss of about $1.3 billion reflects payment timing. The real pressure is compute: $71 billion due within 12 months, $9 trillion long-term, and nearly $96 billion in cash covering only about 16 months of runway.
Title
Anthropic's $85 Billion IPO and the $9 Trillion Compute Bill Behind It
Meta Description
Anthropic files for IPO, expected to raise about $85 billion net from the public offering plus private placement. Revenue grew roughly 13x in a year and operating cash flow turned positive, but a $9 trillion long-term compute commitment and a $71 billion near-term bill reveal the compute gamble behind this financing.
Article Content
Anthropic's IPO prospectus has shown the market a bundle of contradictions: on one side, dazzling numbers with revenue up roughly 13x in a year and operating cash flow flipping from negative to positive; on the other, long-term compute procurement commitments totaling as much as $9 trillion. The AI company behind Claude is using an unprecedented fundraising round to stock up ammunition for an equally unprecedented compute bet.
Deal Structure: More Than an IPO
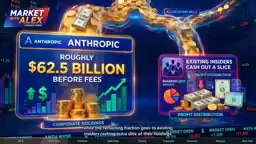
According to analysis by the YouTube channel Market with Alex, Anthropic's prospectus shows the company plans to issue 825 million shares at a price range of $70 to $78 per share. At the top of the range, the public offering alone exceeds $64 billion. The vast majority of the shares are newly issued Anthropic stock, with the company itself receiving about $62.5 billion before fees, while the remainder comes from existing insiders selling down.
Bundled with the IPO is a separate $26 billion private placement. Google and Nvidia have each committed to buy $10 billion as anchor investors. Even at the midpoint of the price range, combining the public offering and the private placement, Anthropic is expected to net about $85 billion in cash.
This fundraising scale would be rare in any industry, but in the context of the AI infrastructure race, it looks more like money forced out by the bills.
Private Placement refers to a financing method in which an issuer sells securities non-publicly to a small number of specific investors (usually institutional or strategic investors), as distinct from a public IPO. Privately placed shares typically carry lock-up periods and do not require the full registration and disclosure process of a public offering, so they can be completed faster and at lower cost. In this case, the $26 billion private placement runs alongside the IPO, with Google and Nvidia each subscribing $10 billion as "anchor investors"—institutions that commit to large subscriptions before pricing, whose participation often signals confidence in the offering and helps attract other investors. This "IPO plus simultaneous private placement" structure is common in tech listings with huge fundraising needs and strategic shareholder support.
Growth Engine: 13x Revenue and Usage-Based Billing
What underpins this massive fundraising is Anthropic's stunning revenue growth curve. The prospectus shows revenue of about $2.5 billion in the first nine months of 2025, surging to $33.2 billion in the same period of 2026—roughly 13x the prior year.
More important is the revenue mix: about $4 of every $5 in revenue comes from usage-based billing. That means when enterprise customers plug Claude into customer service systems, engineering teams, or legal workflows, every API call and every token processed turns into revenue. The deeper a customer rolls out Claude internally, the more revenue it generates. This model gives Anthropic powerful expansion within customer accounts, but it also embeds a hard constraint: every new workload requires real compute to support it.
The "Two Clocks" of Cash Flow and Profit
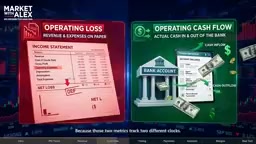
The most confusing part of the financials for investors is the huge gap between operating cash flow and operating profit. Comparing the same two nine-month windows, Anthropic went from about $2 billion in net operating cash outflow last year to $6.6 billion in net operating cash inflow this year. Yet over the same period, the income statement shows an operating loss of about $1.3 billion.
How can a $1.3 billion loss produce $6.6 billion in cash? The reason is that the two metrics track different dimensions of time. Operating loss measures revenue and expenses recognized on paper, while operating cash flow tracks actual money moving in and out of the bank account. Cash prepaid by enterprise customers may arrive in Q3, while cloud vendor bills are not paid until Q4. Both numbers are real, and both can absolutely be true at the same time.
It is worth noting that part of the cash flow improvement comes from better operating performance, and part comes from favorable timing between customer payments and vendor settlements. That timing gap will not always swing in a favorable direction.
The difference between operating cash flow and operating profit centers on the accounting distinction between the accrual basis and the cash basis. The income statement is recognized on an accrual basis: revenue is recognized when performance obligations are fulfilled, and expenses when incurred, regardless of when cash actually changes hands. The cash flow statement tracks real cash movements. The gap between the two shows up mainly in "changes in working capital"—increases and decreases in accounts receivable, deferred revenue, accounts payable, prepaid expenses, and similar items. When customer prepayments rise while vendor payables remain unpaid, operating cash flow can be significantly higher than operating profit; the reverse also holds. Therefore, when analyzing cash flow quality, it is necessary to distinguish "sustainable operating improvement" from "one-time working capital release," since the latter cannot be relied on long term.
The $9 Trillion Compute Bill and a 16-Month Runway
What really makes this IPO seem reasonable is another set of numbers in the prospectus. Anthropic has about $6.6 billion in cash on hand, but procurement and lease commitments due within the next 12 months total about $71 billion—almost entirely related to compute and the physical infrastructure needed to run it.
Extending the timeline into the 2040s, total procurement and lease commitments listed in the prospectus come to about $9 trillion. In other words, even though Anthropic held nearly $96 billion in cash and equivalents by the end of September, against a near-term compute bill of $71 billion a year, that buffer only lasts about 16 months.
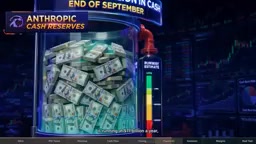
This explains why a company whose operating cash flow has already turned positive still needs to ask Wall Street for tens of billions of dollars. Anthropic needs the money to take delivery of servers, cover operating costs, and bridge the gap between decades-long infrastructure leases and monthly billing to customers.
Runway is a common metric in startup and tech financial analysis, referring to the number of months or years a company's cash on hand can sustain operations at its current burn rate without raising more money, typically calculated as "cash and equivalents ÷ net cash burn over the period." But the runway calculation in this case is unusual: the denominator is not simply operating cash burn, but also incorporates the $71 billion in procurement and lease commitments due within the next 12 months. Such commitments are mostly operating leases and non-cancellable purchase contracts, which may not be fully reflected as current expenses in accounting but constitute rigid cash outflow obligations. Therefore, when assessing the financial safety of AI infrastructure companies, on-balance-sheet cash and off-balance-sheet commitments must be examined together; looking only at book cash can easily overstate true buffer capacity.
The Timing Mismatch of the Business Model
The deeper contradiction Anthropic faces is a timing mismatch between demand and supply. Enterprise customers can decide next week to roll Claude out to tens of thousands of engineers, but building and deploying large-scale compute capacity must be locked in well in advance. Anthropic has no choice but to sign binding compute contracts before it knows exactly how much customers will use.
There are real business reasons for doing so: if compute constraints slow Claude's responses, customers may delay rollouts or even shift workloads to competitors. But the trap is that if rollouts are delayed or usage falls short of expectations, vendor agreements still require Anthropic to pay strict minimum amounts. Whether the servers are used or not, the bill must be paid.
The Vendors Are the Shareholders
In that $26 billion private placement, Google and Nvidia each put in $10 billion—an arrangement worth examining closely. Google provides the cloud computing capacity Anthropic needs to run Claude, and Nvidia sells the hardware that fills data centers. Both giants have clear commercial incentives to ensure Anthropic has cash to serve more customers and pay infrastructure bills.
More infrastructure spending is better for the vendors. But for IPO investors, the math works differently: shareholders only get the profit left after Anthropic pays its compute costs.
The conflict of interest between anchor investors and strategic investors is a structural issue worth watching in this case. Google is both Anthropic's cloud service provider (supplying compute through its cloud platform) and its shareholder; Nvidia is both a GPU hardware supplier and a shareholder. This dual "supplier-shareholder" identity is not uncommon in the AI industry, but it creates misaligned incentives: vendors want Anthropic to procure as much compute and hardware as possible, thereby maximizing their own revenue; IPO investors' returns, meanwhile, depend on the profit Anthropic retains after paying those costs. In other words, vendors benefit from every dollar of Anthropic's capital expenditure, while outside shareholders bear the risk of whether future revenue can cover those fixed costs. When analyzing such companies, particular attention should be paid to the fairness of related-party transaction pricing and the influence of vendor-shareholders on the board.
What Investors Should Watch
Locking in compute has its rationale. If enterprises expand from using Claude as a coding assistant to code review, test writing, and legacy system maintenance, each step gives Claude more work to do. As long as the cost of running each task falls faster than the price Anthropic charges customers, usage growth can translate into healthier margins.
The risk is a classic margin squeeze. If competitors push prices down while Anthropic's growing share of compute is locked in at fixed rates, the math gets hard. The company can run more tasks and report record revenue, but keep less money from every dollar of sales.
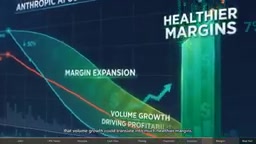
According to Market with Alex's advice, once Anthropic begins reporting as a public company, two things should be watched: first, whether revenue grows in step with gross profit as each new chunk of compute capacity comes online, proving that serving customers really does leave more money behind; second, whether the company can still generate positive operating cash flow as the $71 billion in vendor payments come due. Several consecutive quarters of improvement on both fronts would be more informative than any single record-revenue headline.
Anthropic's IPO gives it the money to lock in compute before customers need it. The real test for shareholders only begins when the compute comes online and the bills come due.
One-line Summary
Anthropic plans to net about $85 billion through an IPO and private placement to support $9 trillion in compute commitments.
Paragraph Summary
Anthropic's IPO prospectus reveals a contradictory entity combining rapid growth with enormous commitments. The company plans to issue 825 million shares at $70 to $78, plus $10 billion private placements from each of Google and Nvidia, for expected net proceeds of about $85 billion. Supporting this fundraising is roughly $33.2 billion in revenue for the first nine months of 2026, up about 13x year over year, with about four-fifths from usage-based billing. Operating cash flow has flipped from $2 billion net outflow to $6.6 billion net inflow, but the income statement still shows an operating loss of about $1.3 billion, a gap driven by payment timing. The real pressure comes from the compute bill: about $71 billion in commitments due within 12 months, roughly $9 trillion long-term, with nearly $96 billion in cash covering only about 16 months of runway. The article concludes that investors should watch whether revenue and gross profit grow in tandem as new compute comes online, and whether cash flow can stay positive after large payments come due.
Related articles

No Coding Required: He Shipped an App Store App by 'Cutting Features' and Nitpicking with AI
A game designer with zero frontend/backend skills shipped a dual-platform App Store app with AI—not via one-click generation, but by cutting scope and nitpicking like a demanding client.

What Is Harness Engineering? From Concept Origins to Enterprise-Level Agent Implementation
What is Harness Engineering? This article traces the concept's origins and analyzes enterprise-level Agent requirements for tool call fault tolerance, data security, tenant isolation, and memory gaps.
Coze in Practice: A Three-Tier Agent Classification and a Multi-Agent Collaboration Guide
A Bilibili tutorial breaks down the multi-agent collaboration toolchain into three categories: building platforms like Coze Studio and Dify, Agent software like Claude Code, and development frameworks like LangChain—plus a Coze demo of industry templates, three-platform interoperability, local Agent integration, and the trade-offs of credit consumption.